DSCR Loan Requirements: How to Qualify for a Rental Property Loan
Explore this guide
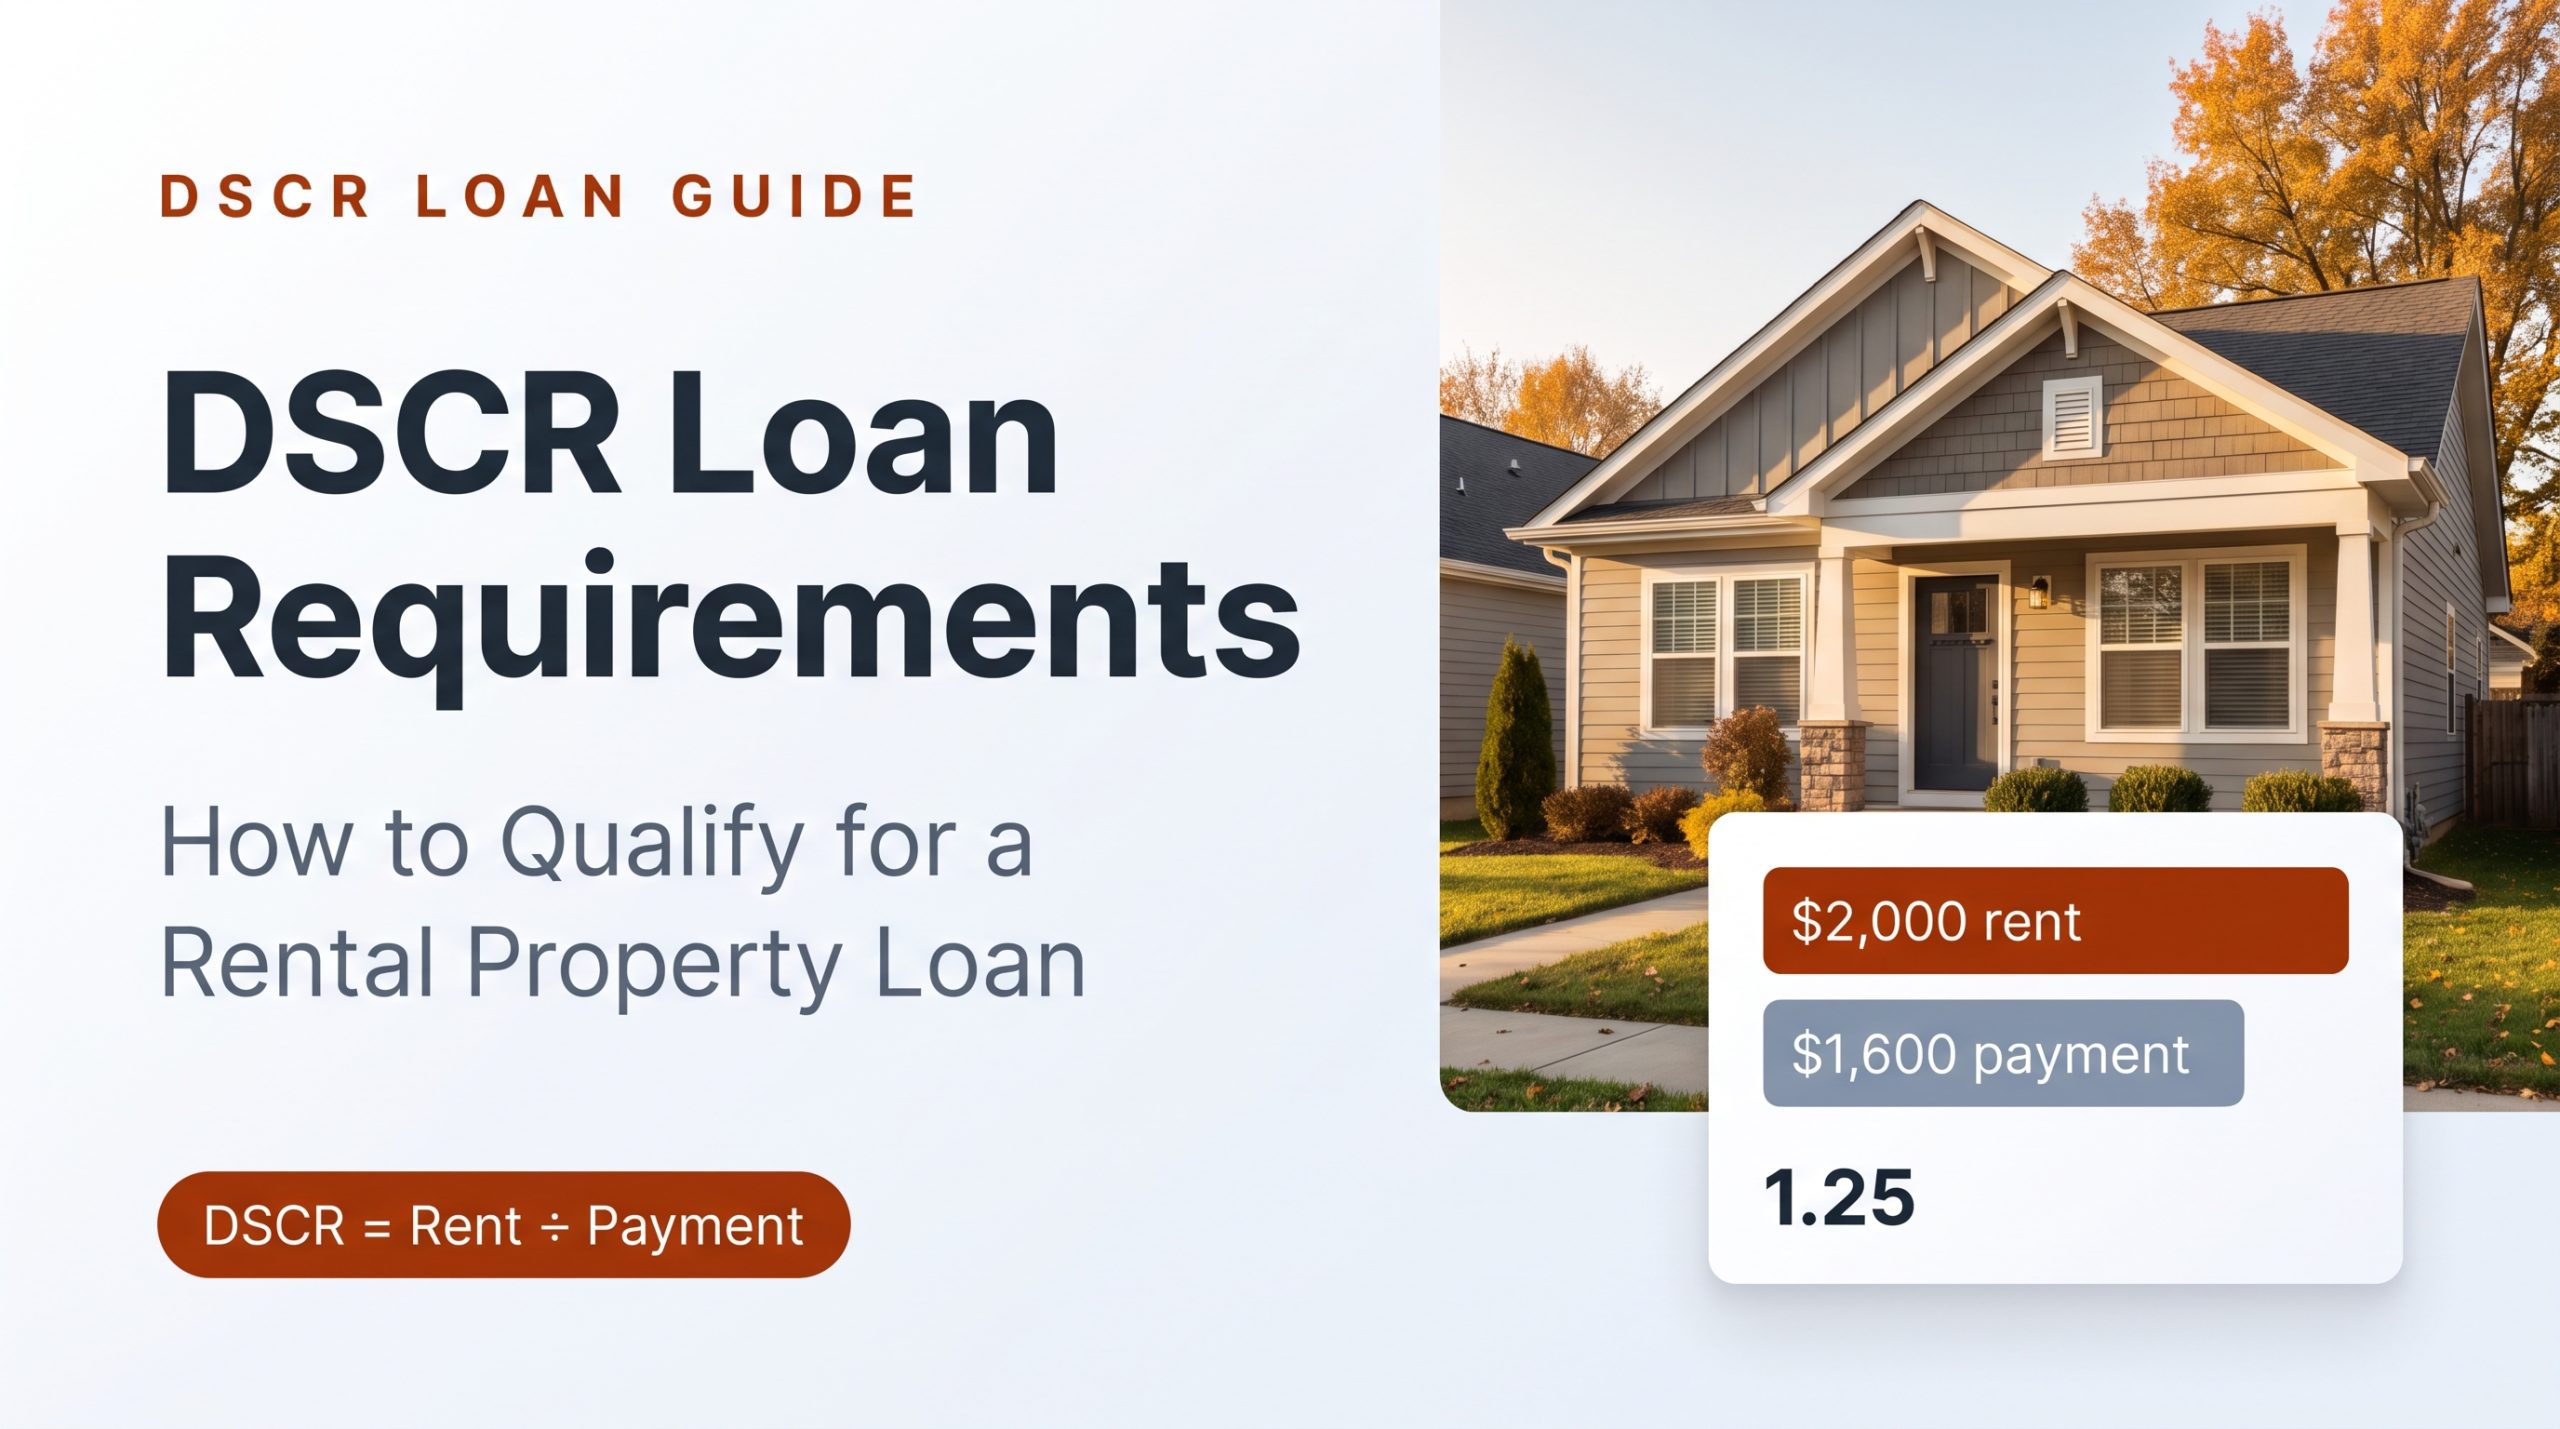
A rental brings in $2,000 a month and the proposed housing payment is $1,600. It sounds like a promising loan candidate. But will a lender actually approve it?
First, calculate the ratio that most DSCR lenders examine. Then check the four other conditions that can change the decision. By the end, you will know which numbers and documents to take to a lender.
Quick answer: A DSCR loan is a rental property loan primarily underwritten using the property’s income and debt payment rather than conventional personal income documentation. Lenders still review the borrower, property, available funds, and loan terms; specific requirements vary.
The First Test: Does Your Rental Income Cover the Payment?
DSCR means debt service coverage ratio. It compares qualifying rental income with the property’s monthly debt obligation. For a simple screening estimate:
DSCR ratio = qualifying monthly rent ÷ monthly housing payment
For many one to four unit rental DSCR programs, the payment includes principal, interest, property taxes, insurance, and applicable homeowners association dues. The lender’s method for eligible rental income and expenses may differ, so confirm its calculation.
For our rental, $2,000 divided by $1,600 produces a DSCR ratio of 1.25. The rent is 125% of the calculated payment. That sounds encouraging. Yet a lender could still decline the application. The next five checks explain why.
What is your DSCR ratio?
Try your own rental figures to see the first qualification indicator.
The qualifying rent exceeds the payment.
This simple estimate does not determine lender eligibility. Confirm the lender’s income and payment calculation.
DSCR Loan Requirements: The Five Checks That Can Make or Break Approval
There is no universal DSCR loan rulebook. These are illustrative ranges commonly seen in investor lending, not a quote or promise of eligibility.
| Requirement | Typical consideration | What to prepare |
|---|---|---|
| DSCR ratio | Some programs consider 1.0 or below; a ratio around 1.20 to 1.25+ may improve options | Lease and rent documentation; obtain each lender’s rental income rules |
| Credit profile | Minimum scores differ; some programs start around the mid 600s or higher | Check your credit report and correct errors |
| Down payment / equity | Many purchase programs require roughly 20 to 25% or more | Document cash to close and closing costs |
| Cash reserves | Often several months of payments after closing | Have recent bank or asset statements ready |
| Eligible property | Often 1 to 4 unit non owner occupied rentals; condo and short term rental rules vary | Address, property details, leases, insurance and HOA information |
Here is the catch. Even with a 1.25 ratio, limited reserves or a low credit score may narrow your options. And what if the ratio is not even 1.0? There may still be paths worth examining.
How to Qualify for a DSCR Loan if Your Ratio Is Under 1.0
A ratio under 1.0 means the qualifying rent is lower than the calculated monthly payment. It is not always an automatic rejection: some lenders offer lower DSCR programs, often with tighter terms, more equity, or stronger reserves.
- Increase the down payment to reduce the loan amount and potentially the monthly payment.
- Compare available insurance costs and validate the property’s taxes and HOA charges.
- Ask whether an interest only option exists, and assess its later payment increase and total cost.
- Confirm whether the lender will use a signed lease, market rent from an appraisal, or another permitted method.
This is where comparing programs becomes important: a property that falls short under one lender’s model could be assessed differently under another. Lower monthly payments may also involve trade offs in pricing or risk.
Can You Get a DSCR Loan for an LLC?
Many lenders allow investment properties to be purchased or refinanced through an LLC, subject to their entity and guarantor rules. A DSCR loan for LLC borrowers may require formation documents, an operating agreement, an EIN, and information about the people who own the company. Personal guarantees are common.
An LLC does not automatically protect a borrower from every liability or change the underwriting result. Discuss entity structure, insurance, and legal protection with qualified advisers.
Buying Another Rental, or Using a DSCR Cash Out Refinance?
The same general income based approach can support different investor goals:
- Purchase: Finance a new eligible rental property using the lender’s evaluation of rental income and your borrower profile.
- DSCR cash out refinance: Replace an existing eligible rental mortgage with a larger loan and potentially access some equity, subject to lender limits and closing costs.
Cash out refinances can have lower maximum loan to value limits and ownership seasoning requirements than purchase loans. Because a refinance increases or changes debt, consider whether the future rental income comfortably supports the new payment.
The Documents to Gather Before You Apply
- Purchase contract for a purchase, or existing mortgage statement for a refinance.
- Current leases, rent roll, and any requested rental income evidence.
- Recent bank or asset statements showing funds and reserves.
- LLC formation documents and EIN records, if applying through an entity.
- Insurance details and any HOA or property tax information available.
An appraisal, title review, and additional specific to each lender documents may also be required. Preparing the basics early can reduce avoidable back and forth, although it does not guarantee a closing date.
One Last Check Before You Choose a Lender
Two lenders can look at the same rental and offer different rates, loan amounts, prepayment penalties, points, cash reserve requirements, and eligibility decisions. Compare the full terms, not only the advertised rate.
LoanBidz is a broker that can help you compare available lender options. If you already know your estimated rent, payment, credit range, and available cash, you have the starting information for a more useful conversation.
Frequently Asked Questions About DSCR Loans
Do DSCR loans require personal tax returns?
Many DSCR loan programs do not use personal tax returns or W2 income for standard income qualification. Lenders may still request identification, asset records, entity information, or other documents.
What is a good DSCR ratio?
A 1.0 ratio means qualifying rent equals the calculated payment; 1.25 means rent is 25% higher. Some lenders favor ratios at or above roughly 1.20 to 1.25, but requirements and pricing vary.
Can a first time investor qualify for a DSCR loan?
Some lenders accept first time investors, sometimes with additional reserve, equity, or credit requirements. Ask about experience rules early.
How long does a DSCR loan take to close?
It depends on appraisal, title, property, and lender processing. Complete documents help, but no particular closing timeline is guaranteed.
Ready to Find Out if Your Rental Qualifies?
Remember the rental earning $2,000 with a $1,600 payment? Its ratio of 1.25 passed the first test, but not every test. With the ratio, credit profile, available equity, reserves and property details together, you can now ask lenders a much better question: which available program fits this specific investment?
Educational information only. Program availability, rates, loan to value limits, and documentation requirements vary by lender and may change. Financing is subject to underwriting and approval.
 Previous Post